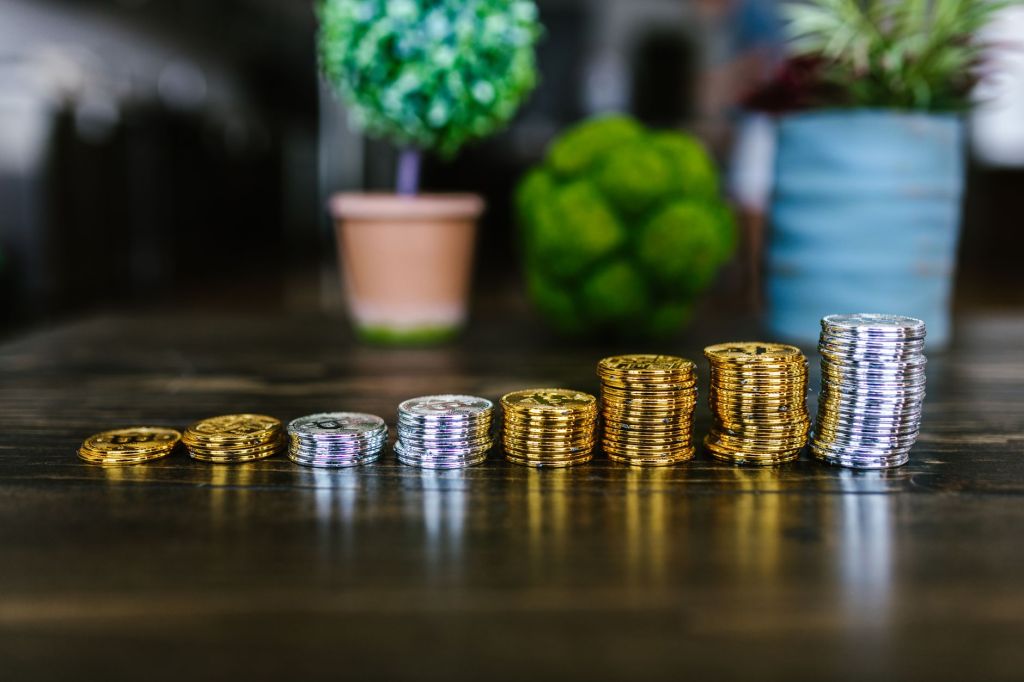
With the holidays quickly approaching, it is time to think about all the end-of-the-year tasks that we dread, look forward to, and procrastinate on. Beyond gift buying and gift giving, this extends to your personal financial matters. One of the most important things you can do to be financially independent is to set yourself up for future success by saving for retirement. This does not just mean placing money aside earmarked for retirement. It means putting that money to work by investing it into financial vehicles that will in turn compound that initial lump sum into a bigger sum over time.
Every year, we all have the year’s retirement contribution limits to contend with. By contributing to these retirement accounts whether it is a traditional or Roth IRA, 401(k), 403(b), etc., you are taking care of yourself by positioning yourself towards a better future financial position. While it is much easier to embrace the mindset of treating yourself now, playing the long game will reap the benefits to heights you really need to see to believe. Check out this compound interest calculator and punch in the numbers to model different scenarios to fully visualize and appreciate how your money can work for you.
It is always a regret of investors that they did not start earlier. But as the saying goes, the next best time to invest is now! Don’t procrastinate and put it off to next time, next month, or next year. Investing small amounts now leads to bigger growth over time compared to investing larger amounts later. The key factor is the time horizon. Do not let that deter you if you are starting later or are feeling down about not having as much time now before your retirement age. The returns will continue to be less impactful the longer you wait. You can only do what you can with what you have now. Don’t beat yourself up for not doing things earlier. You can only move forward with what you know and do now.
Keep in mind that each year there are new contribution limits to what you are able to add to retirement accounts based on your age and the type of account. Make sure you are taking advantage of all the accounts at your disposal to contribute to. Some accounts you are only eligible for based on whether you meet the income eligibility criteria or if your workplace/job position allows for contributing to such an account.
Please do yourself a huge favor and contribute as much as you can towards the limits for this year! And gearing up for next year, there may be options offered to automatically contribute a certain percentage of your paycheck to the retirement account. On top of that, there may be an additional option to automatically increase that percentage every year. This simple action of automation keeps it out of mind and out of sight so there’s no need to set reminders or take the time to manually go through and contribute in a tedious clockwork fashion.
Now once you have done all that, please make sure that any contributions you add to a retirement account is actually invested in something and not just sitting there doing nothing. I believe some brokerages make sure to have an option selected by default, but do your due diligence to make sure that is actually the case or even set it to an option that you want as the new default! I have heard some horror stories of people contributing to retirement accounts thinking that they have done everything right only to find out that the money was not actually invested into stocks or funds! Speaking of, if you’re not sure what to invest in, a good standard option is a target retirement fund based on the year you plan to retire. Then, as you get your bearings about personal financial matters, you can choose a different investment if you would like!
Disclaimer: This content is for informational purposes only and should not be construed as legal, tax, investment, financial, or other advice. Please conduct your own research and due diligence before making any financial decisions.


Leave a Reply